technology
The Portfolio vs. The Single Bet
Why the Person Who Builds It Almost Never Owns It There is a moment in every recording contract negotiation where the artist's lawyer asks about the recoupment structure, and the label's lawyer explains it patiently,…
Why the Person Who Builds It Almost Never Owns It
There is a moment in every recording contract negotiation where the artist's lawyer asks about the recoupment structure, and the label's lawyer explains it patiently, and the artist nods because they understand the words. Then they sign, because the alternative is going home without a deal. Six months later, when the single has 10 million streams and the royalty statement shows a negative balance, the artist finally understands what they agreed to. Not the words. The maths.
The same moment happens in a different room when a first-time founder signs a term sheet with a 1x participating liquidation preference and does not model what their 65% equity stake is actually worth under a realistic exit scenario. It happens when a developer signs an employment contract with an IP clause covering "all work product, whether created during or outside working hours, that relates to the company's business or anticipated business." It happens when a freelance designer signs a work-for-hire agreement that transfers copyright in perpetuity for a flat fee.
These are not the same industry. They are the same financial transaction, dressed in different clothes. And the first step toward navigating it is understanding that you are not dealing with a creative business. You are dealing with a financial one.
Every creative industry is a financial industry
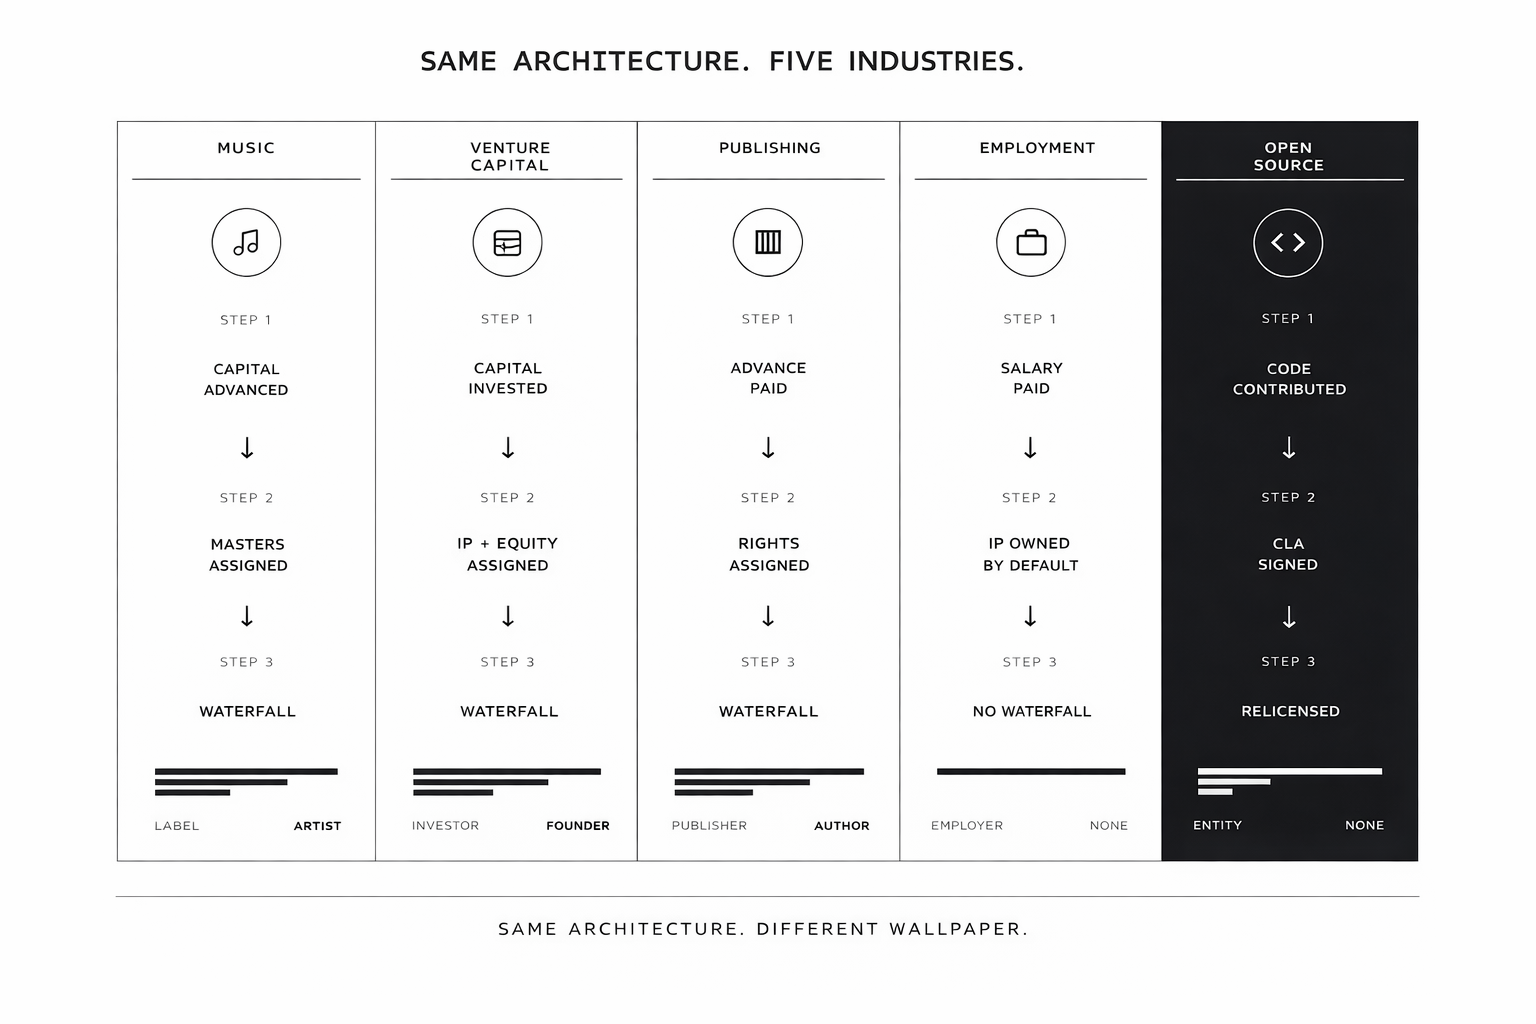
A record label is a fund. So is a publishing house, a film studio, and a company that hires employees. They all do the same thing: pool capital, deploy it across a portfolio of uncertain bets, and structure the contracts so the rare winners compensate for the frequent losers.
This is not a metaphor. A bank's loan book is a portfolio. Individual borrowers default, but interest income from performing loans covers the losses. An insurance company pools premiums across thousands of policyholders, and the actuary's job is to ensure the pool absorbs individual claims without breaking. A private equity firm buys ten companies, restructures them, and knows that three or four exits need to carry the fund. A stock portfolio diversifies across uncorrelated positions so no single loss is fatal.
The creator, in every one of these industries, is the equivalent of a single loan, a single policy, a single stock. They cannot pool their own risk. That asymmetry is the entire game.
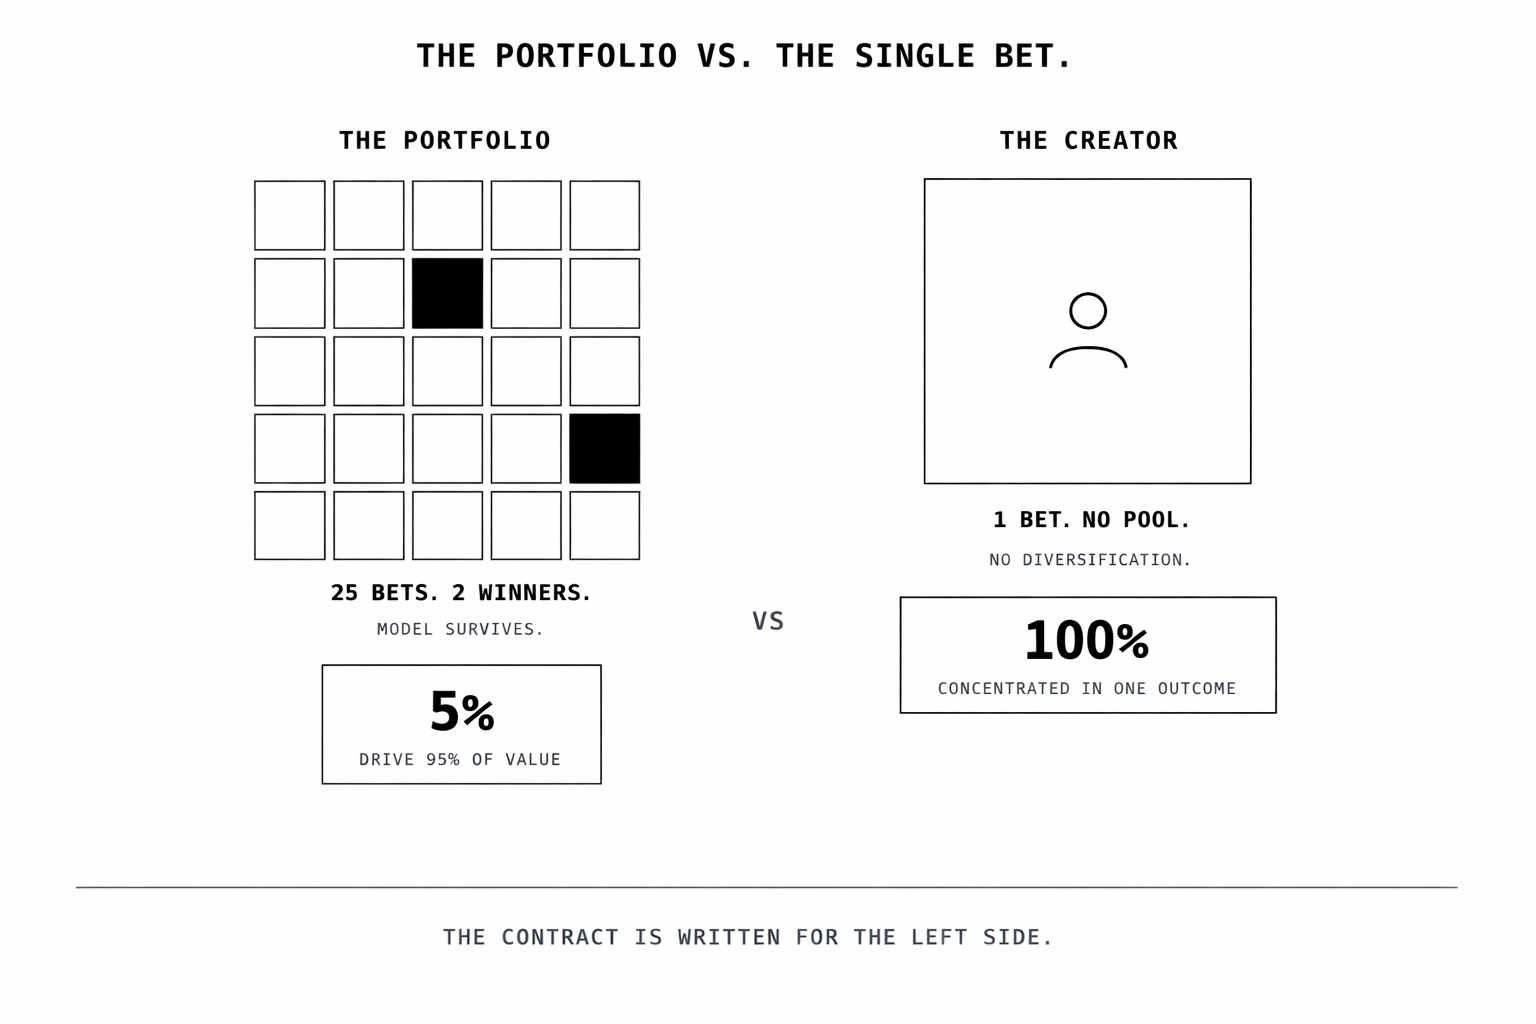
But here is the thing most creators miss: the portfolio model is not reserved for people with capital. It is a way of thinking, and creators can adopt it too. More on that shortly.
The power law makes the contracts non-negotiable
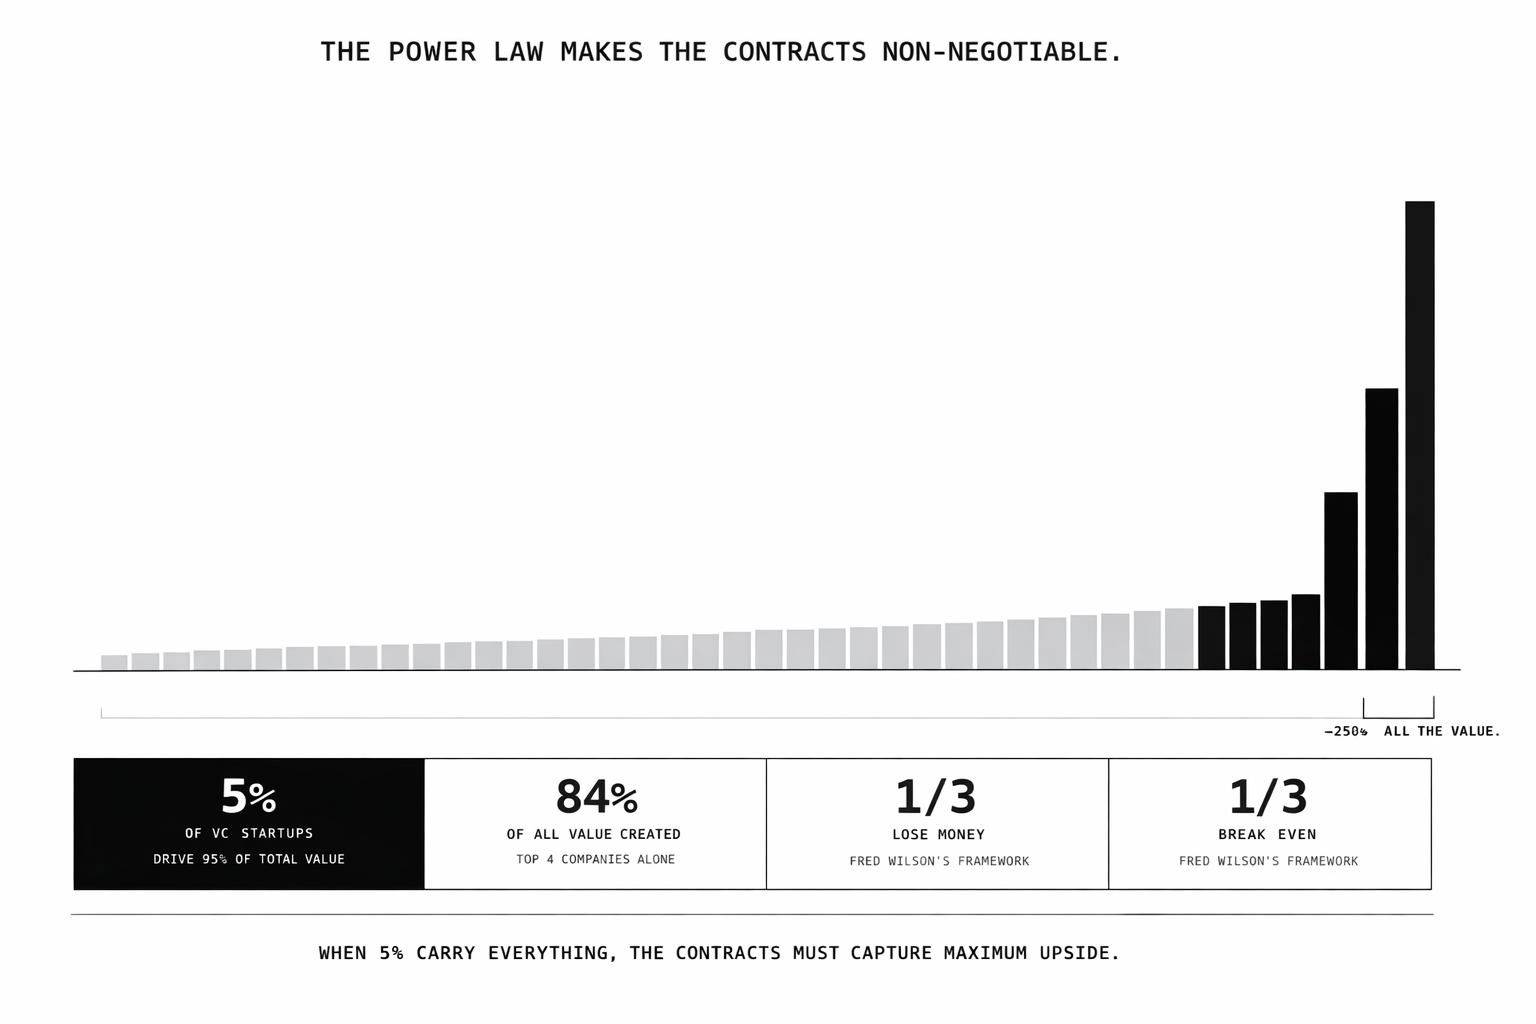
Fred Wilson, one of the most respected venture capitalists in the world, has described the maths plainly. An early-stage venture fund expects to lose money on a third of its investments, break even on another third, and generate real returns on only the final third. And within that top third, a single deal often needs to return a multiple of the entire fund to make the model work.
Y Combinator's data shows how extreme this gets. Across more than 5,000 funded startups, roughly 5% account for over 95% of the portfolio's total value. The top four companies alone, Airbnb, DoorDash, Coinbase, and Instacart, represent more than 84% of all market value created. Everything else is a rounding error.
This is the power law, and it is not unique to venture capital. Record labels see the same distribution: a handful of artists generate the revenue that sustains the entire roster. Publishing houses depend on a few bestsellers to fund hundreds of books that never earn out. Film studios greenlight thirty projects knowing three will be profitable.
When outcomes are this skewed, the portfolio entity has no choice. The contracts must capture maximum upside from the few bets that work, because nothing else covers the cost of the many that do not. Liquidation preferences, recoupment clauses, IP assignments, master rights transfers. These are not aggressive negotiating positions. They are survival mechanisms.
This is not something to fight. It is something to understand. The funder is not your adversary. They are running a model that requires certain protections to function, and without that model, most creative and intellectual work would not get funded at all. Your job is not to dismantle their model. It is to know it well enough to negotiate within it, and to build your own model alongside it.
The principal-agent problem shapes most of what you sign
The funder cannot sit in the studio, the office, or the codebase. They cannot observe effort, quality decisions, or honesty in real time. In economics, this is the principal-agent problem: the funder and the creator have misaligned incentives, and the funder cannot directly monitor behaviour. So the contract substitutes for observation.
This is why advances are structured as recoupable loans rather than gifts. If the label simply paid the artist and hoped for the best, the incentive to deliver would weaken. By making the artist's future income contingent on repaying the advance through royalties, the contract attempts to align effort with return.
It is why vesting schedules exist in startups. The investor cannot know whether the founder will still be committed in year three, so equity vests over four years with a cliff. It is why employment contracts assign IP by default: the employer pays a salary upfront and cannot verify that the output will justify the cost. Ownership of the work product is their hedge.
Most clauses in a creative contract can be understood through this lens. That does not make the clauses fair. It makes them predictable. And predictable means you can prepare.
The structural alternative to pure assignment is licensing. Instead of transferring ownership outright, you grant the funder a licence scoped to their specific needs: this product, this territory, this time period. They get what they are paying for. You retain the underlying IP. A consulting client does not need to own every framework you built to deliver their project. A publisher does not need world rights in perpetuity to sell your book in English. The default contract asks for everything because it is easier to draft and eliminates optionality risk. But a narrower grant, scoped precisely, often costs the funder nothing meaningful while preserving your ability to build on your own work in the future.
Asymmetric skin in the game
The combined effect of the power law and the principal-agent problem creates what Nassim Taleb calls asymmetric skin in the game.
The portfolio entity has limited downside. If one bet fails, the others absorb it. If the entire fund underperforms, the managers still collected fees. The structure is designed to make individual failure survivable.
The creator has the inverse. Years of their life invested in a single bet. Opportunity cost that compounds silently. Reputation attached to the outcome. And upside that is capped by a waterfall ensuring everyone else gets paid first. The risk is not shared. It is allocated, and it is allocated before the value exists, at the moment when the creator has the least information and the most need.
The structural response to this asymmetry is not to reject the deal. It is to rebalance the skin in the game where you can.
Revenue-share agreements do this directly. Instead of assigning IP in exchange for an advance, the creator retains ownership and the funder takes a percentage of revenue until a defined cap or multiple is hit. The funder still gets a return. The creator keeps the asset. This model is already common in indie film financing and is growing in music, particularly in the post-streaming era where artists are negotiating distribution deals rather than traditional recording contracts. In software, it shows up as revenue-based financing where the founder retains equity and the funder takes a percentage of monthly revenue until they have been repaid a multiple of their investment.
Reversion clauses are another mechanism. If the funder does not exploit the work within a defined period, the rights revert to the creator. These are standard in some publishing contracts and negotiable in music deals, though rarely offered by default. The creator gets a time-limited commitment rather than a permanent transfer. The funder loses nothing if they are actually using the work, and the creator does not end up with a permanently encumbered asset that nobody is doing anything with.
Taylor Swift's masters dispute made this dynamic globally visible. She signed with Big Machine Records at fifteen, and the deal gave the label ownership of her first six albums' master recordings. When Big Machine was sold to Scooter Braun's Ithaca Holdings for $330 million in 2019, Swift's masters transferred to a buyer she had no relationship with and no power to block. Rather than accept it, she re-recorded the albums under her new deal with Republic Records, where she owns her masters outright. The re-recorded versions outsold the originals. In 2025, she bought back the original masters from Shamrock Capital, finally owning her entire catalogue. The lesson is not that every creator can do what Swift did. She had extraordinary leverage. The lesson is that the structure of her original deal, standard for the industry, meant the most successful recording artist of her generation did not own her own work for nearly two decades. That is the default at work.
How the waterfall works
The waterfall is the sequence that determines who gets paid first when value is eventually created.
View original mediaFrench Montana's "Unforgettable" makes this concrete. The song is certified 11x Platinum, with over 1.8 billion YouTube views and 1.7 billion Spotify streams. Montana spent $600,000 of his own money, $300,000 to clear the sample because Epic Records would not fund it, and another $300,000 to shoot the video in Uganda. He has said publicly that he has not made a dollar from the record. The biggest hit of his career, and the recoupment structure meant the revenue flowed to the label's portfolio first. The waterfall worked exactly as designed.
In venture capital, the waterfall runs through liquidation preferences. An investor with a 2x participating preference on a $5 million investment takes the first $10 million off the table in any exit, then participates again based on equity percentage. Angel investor Peter Cowley described a ten-figure exit in Cambridge where the founder, after a decade of building the company, was "squashed to zero by the prefs."
In publishing, the advance is the waterfall. The author assigns rights, and every book sold reduces the negative balance until earn-out. Most traditionally published books never reach that point.
In employment, there is no waterfall. The employer owns the output. The employee receives a salary. Full stop.
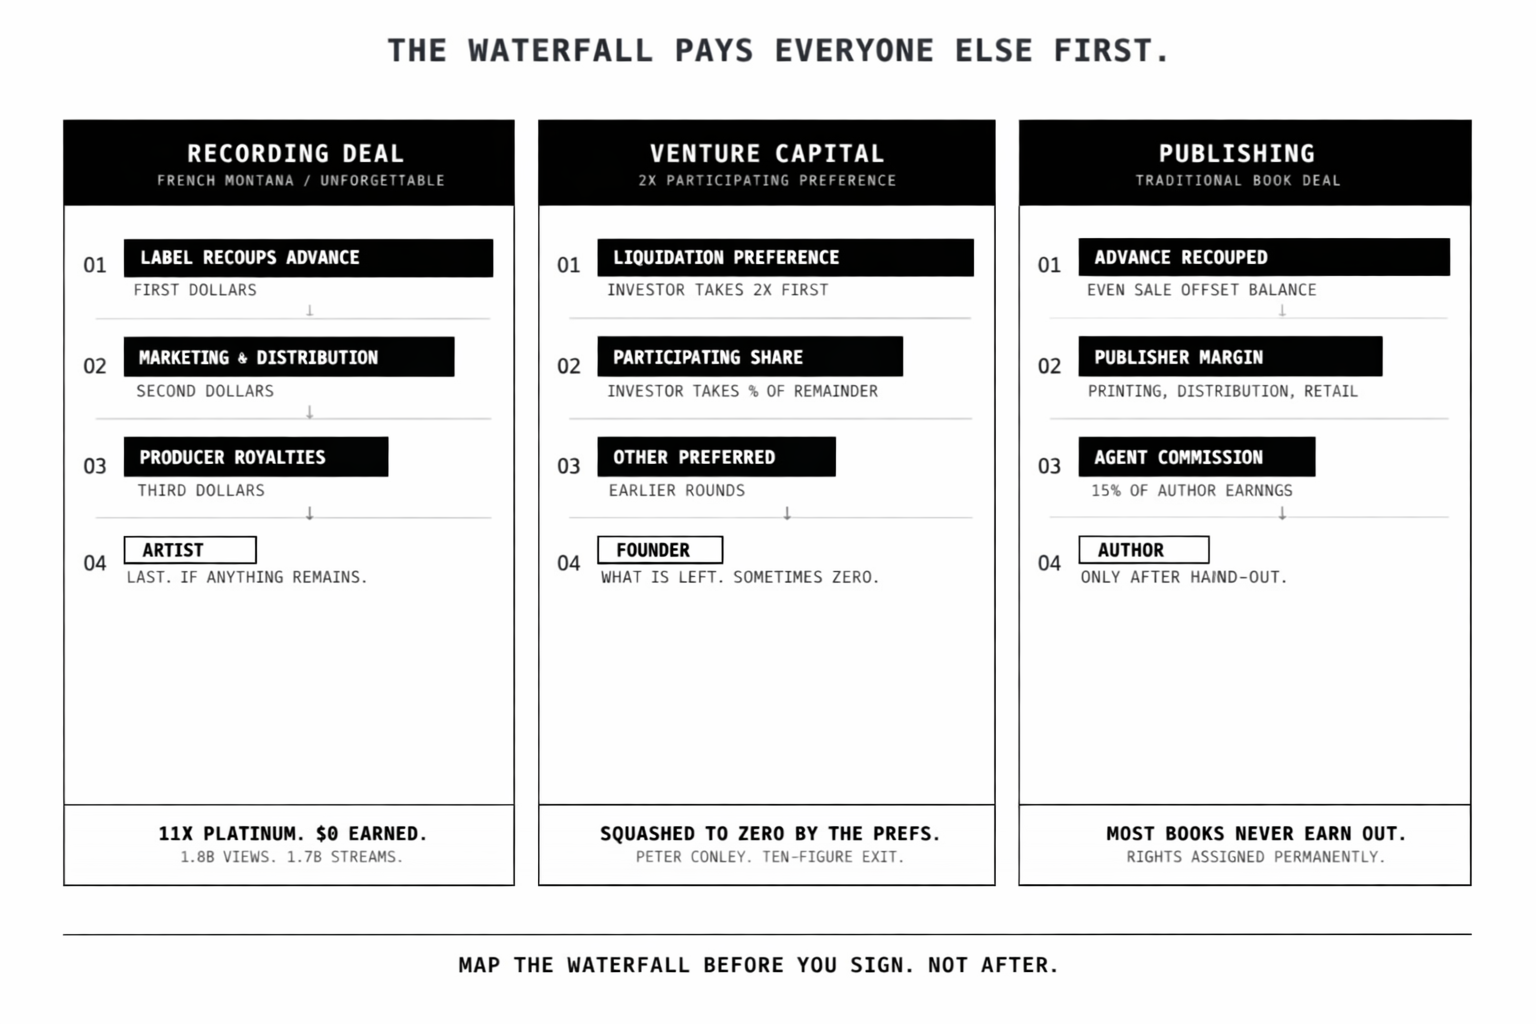
The lesson is not to avoid waterfalls. It is to map them before you sign. If you cannot draw the sequence on paper, showing who gets paid first, second, and last under your specific terms, you do not understand the deal you are entering.
The five transfer moments...
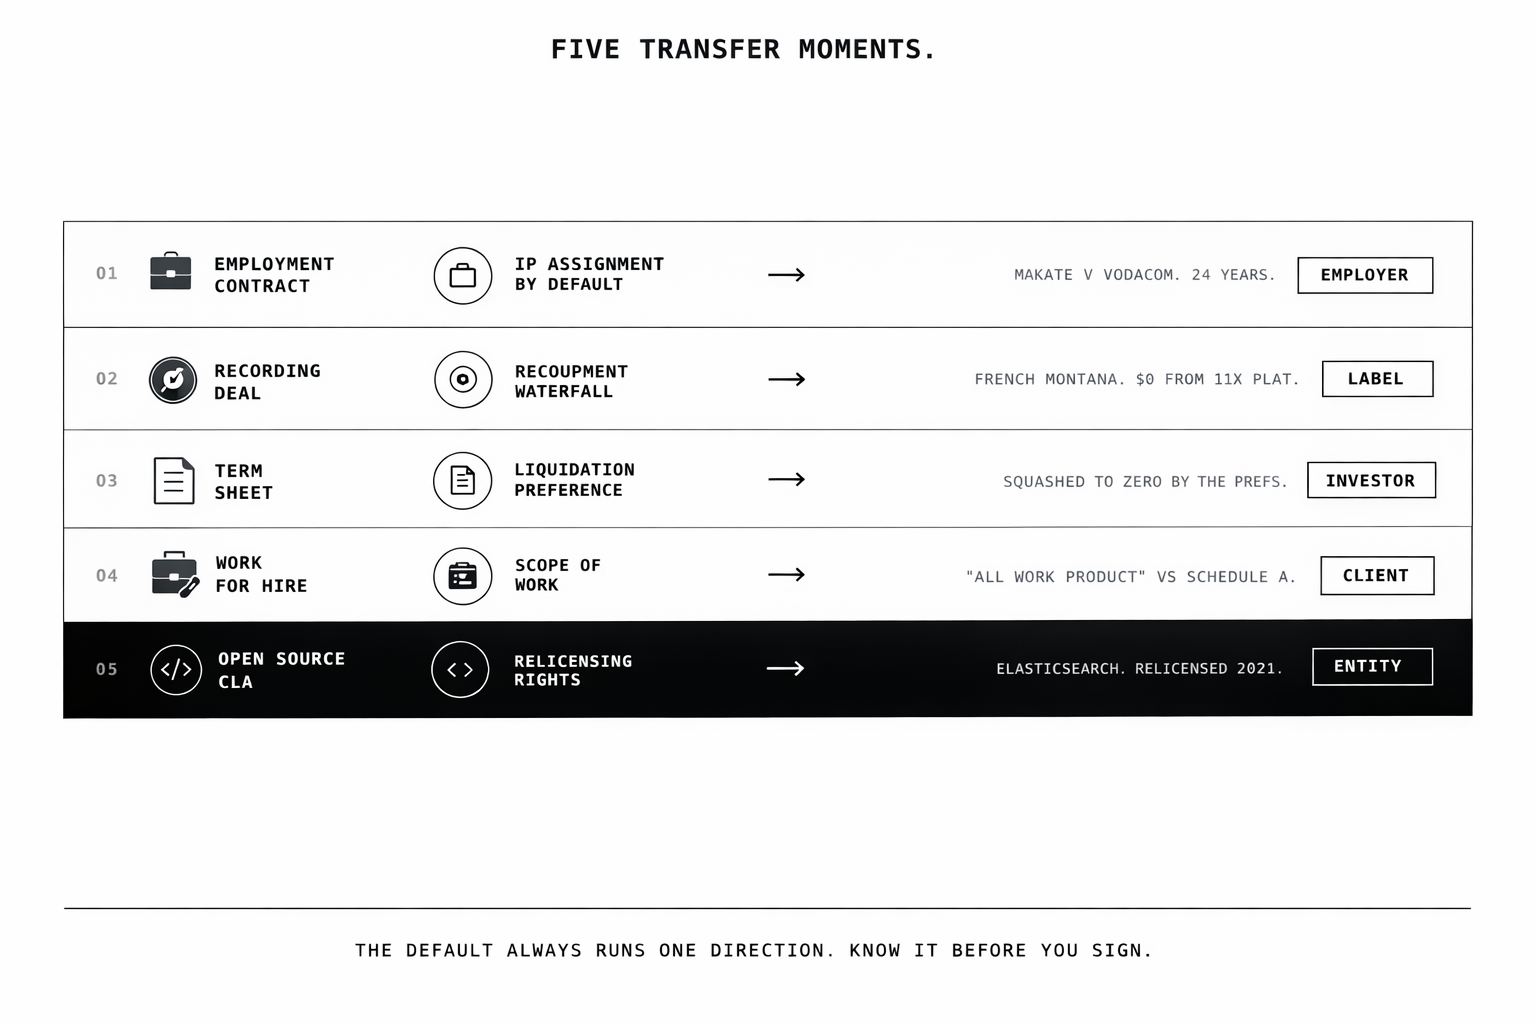
The employment contract. Nkosana Makate came up with Vodacom's "Please Call Me" concept in 2000 as an employee. Vodacom launched the service in 2001 and it generated billions in revenue. Under South Africa's Copyright Act, Section 21(1)(d), the IP was Vodacom's by default. After more than two decades of litigation, Vodacom and Makate settled out of court in November 2025, with the payout estimated at around R700 million based on Vodacom's financial disclosures. Even that settlement is now contested by a litigation funder claiming 40%. A quarter-century of legal warfare, and the man who conceived one of the most successful mobile products in African history is still fighting over his money. The default ran against him from day one. The UK and US have equivalent provisions. Read the clause. Get a written carve-out for personal and existing work. Before you sign.
The recording or content deal. French Montana's situation is the standard outcome, not the exception. Model the recoupment waterfall before you accept the advance. Ask about reversion clauses. Consider whether a distribution deal, where you retain masters and pay a percentage for distribution, gives you better long-term economics than a traditional recording contract. Chance the Rapper built his career entirely without signing a recording deal, retaining ownership of his masters and earning revenue through touring, merchandise, and short-term licensing deals like the one-time $500,000 exclusivity arrangement with Apple Music for his Grammy-winning Coloring Book. That path demands more upfront investment and patience. It also means you keep what you build.
The term sheet. Liquidation preferences, anti-dilution clauses, and IP assignments are the three clauses that most affect founder economics. Draw the waterfall. Model realistic scenarios, not just the headline valuation. Understand that the funder's structure is not adversarial, it is the power law forcing their hand, and negotiate from that understanding rather than from emotion.
The work-for-hire agreement. Push for narrow scope. Grant a licence for the specific deliverables rather than assigning all IP. "The deliverables in Schedule A" versus "all work product" is the entire difference between owning your future work and not.
The open-source CLA. In 2021, Elastic used its CLA's broad relicensing rights to move Elasticsearch from open-source to proprietary licensing, blocking Amazon from offering it as a managed service. Contributors who signed the CLA believing they contributed to an open-source project found their code relicensed under terms they never anticipated. Read what you sign, even when the project feels collaborative. The Developer Certificate of Origin (DCO) is a lighter alternative that many projects now prefer precisely because it avoids the asymmetric power transfer of a full CLA.
Think like a portfolio
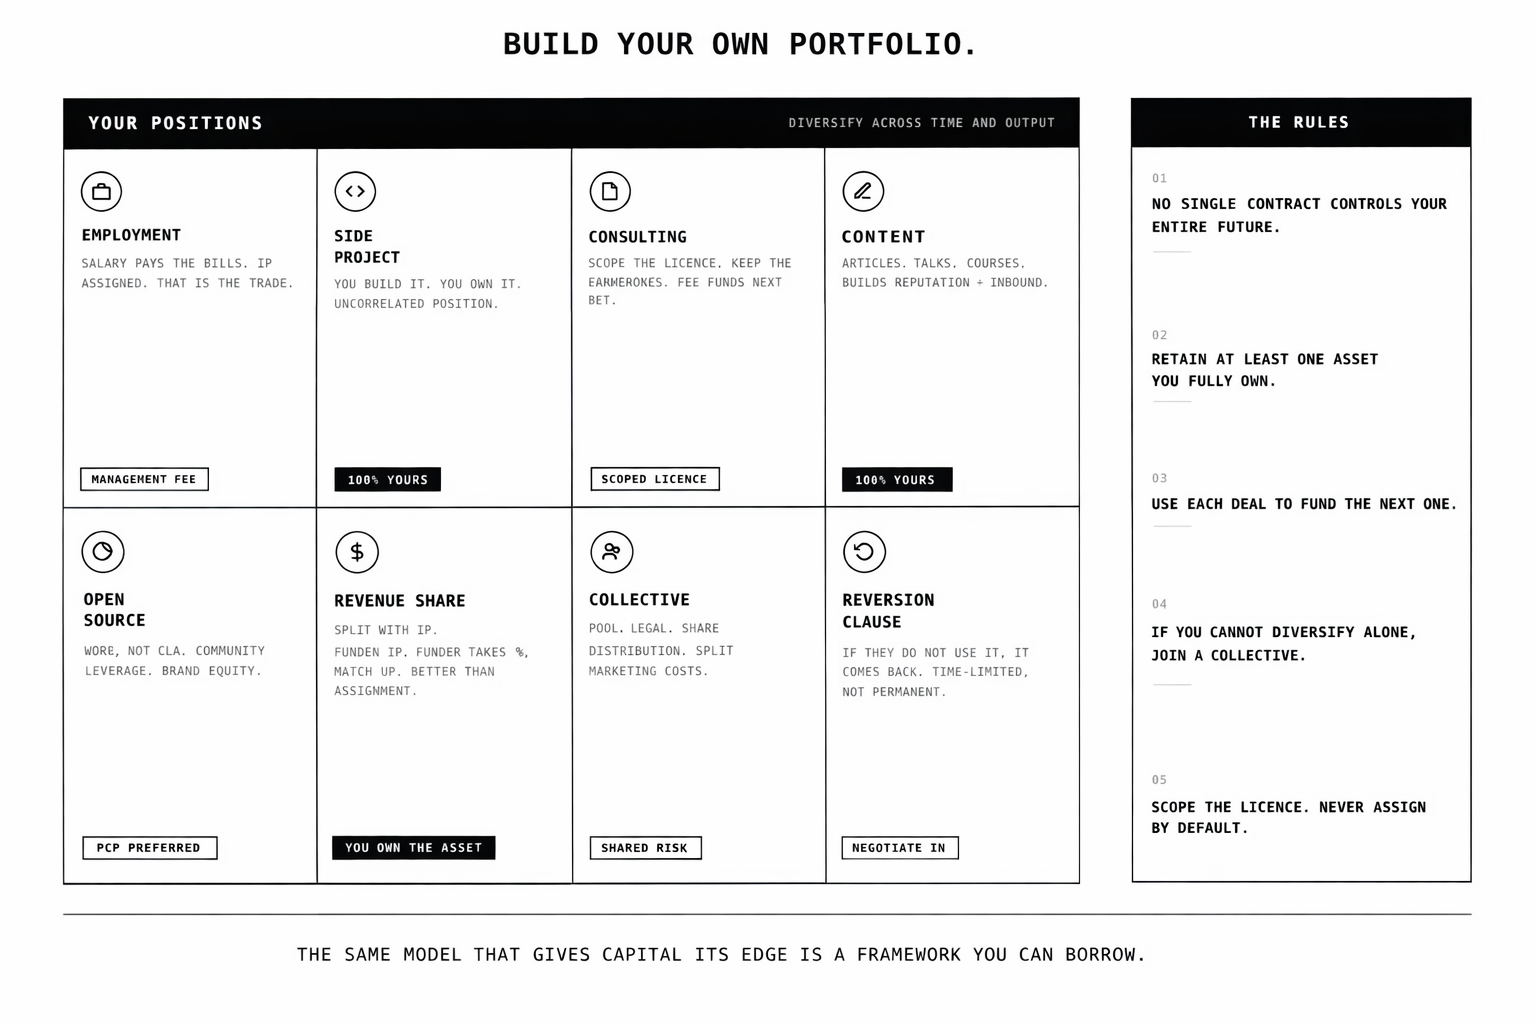
The most important shift a creator can make is not in any single negotiation. It is in how they structure their creative life.
The portfolio model works for the funder because they spread risk across many bets and need only a few to succeed. You can apply the same logic to yourself, not with other people's capital but with your own time and output.
Do not concentrate everything in a single bet. If you are a developer, the employment contract pays the bills, but it should not be the only thing you are building. The side project, the open-source contribution, the consulting engagement, the content you produce, each one is a position in your personal portfolio. Some will go nowhere. A few might compound. The point is that no single contract controls your entire future.
Retain at least one asset you fully own. Even if every other deal involves some form of assignment or licensing, maintain one project where you hold 100% of the IP. That is your uncorrelated position, the one bet in your portfolio that is not subject to someone else's waterfall.
Use each deal to fund the next one. The salary funds the side project. The consulting fee funds the product. The advance funds the time to build something you own entirely. Think of employment and client work as your management fee, the capital that keeps you alive while your personal portfolio matures.
And if you cannot diversify alone, form or join a collective. Groups of creators can pool legal resources, share distribution infrastructure, and split marketing costs. This is exactly what labels, publishers, and studios do. There is nothing stopping creators from doing it at a smaller scale, and some already are. United Masters in music. Indie publishing cooperatives. Open-source foundations that hold IP collectively and distribute it under terms the community controls.
Swift's story is instructive here too. She did not just fight to recover her old masters. She structured her new deal with Republic Records so that she owns every master she records going forward. She separated the fight for what was lost from the architecture of what came next. That is portfolio thinking applied to a creative career.
The only advantage you have
Capital has every structural advantage: portfolio diversification, legal teams, the power law working in its favour, and contracts refined over decades. You are not going to restructure the economics of creative funding.
But you can understand the system before you enter it. The power law explains why the contracts must capture upside aggressively. The principal-agent problem explains why they shift risk to you. Asymmetric skin in the game explains why the downside lands on your side of the table. And the portfolio model, the same one that gives capital its structural edge, is a framework you can borrow for your own creative life.
Read the clause. Map the waterfall. Define the scope. Retain one thing that is entirely yours. These are not advanced moves. They are the minimum. And the distance between signing blind and signing informed.